Hi there! How can we help you today?
Buying a Home
Home Construction Styles: Mud Houses to Modern Mivan
Home construction in India tells the story of a family's dreams, savings and years of hard work. This guide walks throug...
Discover Your Dream Home with Our Latest Listings and Personalized Services!
Join Us for Exclusive Open House Events This Weekend and Find Your Perfect Home!
Take Advantage of Limited-Time Offers on Luxury Homes with Stunning Features!
Explore Our Exciting New Property Listings Now Available in Prime Locations!
NRI property buying in India comes with strict FEMA rules, a freshly updated 2026 tax law, revised TDS sections, home loan eligibility…NRI property buying in India comes with strict FEMA rules, a freshly updated 2026 tax law, revised TDS sections, home loan eligibility norms and Punjab-specific registration steps that every overseas Indian buyer must understand clearly before wiring money or signing a single property document abroad.
Every year, thousands of Punjabi families settled in Canada, the UK, the US, Australia and the Gulf dream of owning a home back in their native city. NRI property buying in India feels personal because it is about your emotions towards your homeland.
Many overseas buyers today specifically look for ready to move flats so rental income or personal use can begin immediately, while others chase luxury apartments that match the lifestyle they have built abroad.
But NRI property buying in India also comes with rules that change quietly and most online guides never catch up. A new tax law came into force on 1 April 2026. If you are serious about NRI property buying in India this year, you need facts that are current, not the old version.
This guide walks you through exactly what changed, what stayed the same and what you need on hand before you sign anything.
Who Actually Qualifies as an NRI?
Before you look at a single property listing, you need to confirm your legal status. Indian law is specific about this and getting it wrong can delay your purchasing property.
Under the Income Tax Act, you are classified as a Non-Resident Indian
There are three categories of overseas buyers and each one has different rights.
NRI (Non-Resident Indian):An Indian citizen living and working abroad. Full buying rights for residential and commercial property.
OCI (Overseas Citizen of India):A foreign citizen of Indian origin holding an OCI card. Treated on par with NRIs for property purchase.
PIO (Person of Indian Origin):Since the 2019 FEMA amendment, a PIO without an OCI card does not automatically get the same permissions as NRIs and OCIs. Separate RBI approval may be needed.
Special Note One more thing that catches people off guard. Citizens of Pakistan, Bangladesh, Sri Lanka, Afghanistan, China, Iran, Nepal, Bhutan, Macau, Hong Kong and North Korea cannot buy property in India without specific RBI approval. This applies even if they are of Indian origin.
This is the part most blogs still get wrong but here we will guide you to the current scenario.
Parliament passed the Income-tax Act, 2025 on 12 August 2025. It received presidential assent on 21 August 2025 and came into force on 1 April 2026. From that date, the Income-tax Act, 1961 stands repealed. The Income-tax Rules, 2026 were notified on 20 March 2026 to make the new law operational, according to the Income Tax Department.
Here is the important part for buyers. This was mostly a drafting exercise, not a policy overhaul. Tax rates, thresholds and your actual obligations have carried over largely unchanged. What changed is where these rules now live inside the law.
More than forty scattered deduction sections were consolidated into one single provision, Section 393. Two changes matter most for property buyers in India.
Section 194-IA (TDS when you buy immovable property) is now Section 393(1).
Section 195 (payments made to a non-resident) is now Section 393(2).
The paperwork changed too. Form 26QB, the challan-cum-statement most buyers and their CAs know by heart, has been merged with Forms 26QC, 26QD and 26QE into a single new form, Form 141.
Along with Form 141 you need to fill Form 16B. If any NRI wants to buy property, they must show Form 16B earlier and now 16B has been replaced with form 132 that you need to show to the seller.
When you pay the seller, you don't hand over the full amount. You cut a small part and deposit it with the government yourself, on the seller's behalf. The form is proof of that deposit.
Example:You buy a 3 BHK flat In Zirakpur worth ₹1 crore. TDS is 1%, so ₹1 lakh goes to the Income Tax Department and the rest of ₹99 lakh goes to the seller. You file Form 141 to report this. Once deposited, you download Form 16B and give it to the seller as proof their tax was paid.
Earlier, if an NRI bought a flat, needs to fill Form 26QB to report TDS. If it was rent, dividend or something else, three other forms came into play: 26QC, 26QD, 26QE. Four separate forms for four situations.
Now, all four are gone. One single form, Form 141,covers all of them.
So today, when you buy a flat and deduct TDS, your CA fills Form 141, not Form 26QB. Same process, same deadline, just one form instead of four. Simpler paperwork, same rules underneath.
The Income Tax Departmentdescribes it as the challan cum statement for payment and reporting of tax deducted under Section 393(1) and it must be filed within one month from the end of the month in which the tax was deducted.
Nothing you owe has changed. What has changed is which form your lawyer or chartered accountant should be filing and which section they should quote in your sale deed and TDS certificate.
If a property agent, developer or online guide is still talking about Form 26QB or Section 194-IA for a transaction happening after 1 April 2026, that source has not caught up. Transactions completed up to 31 March 2026 still follow the old forms.
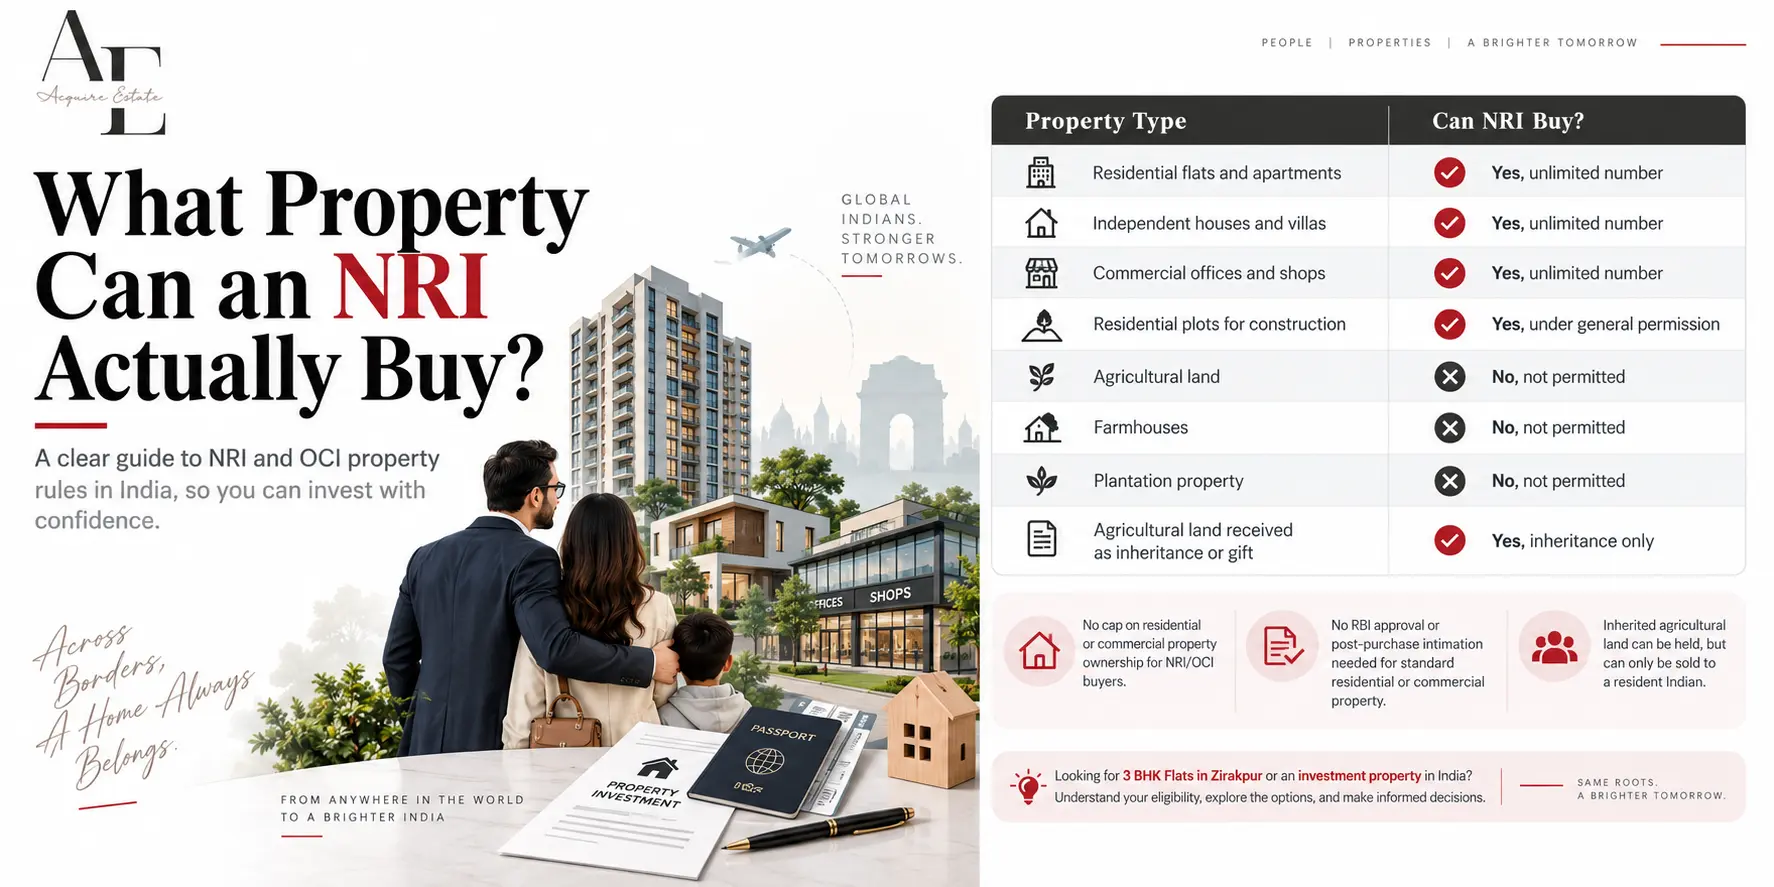
Property Type | Can NRI Buy? |
Residential flats and apartments | Yes, unlimited number |
Independent houses and villas | Yes, unlimited number |
Commercial offices and shops | Yes, unlimited number |
Residential plots for construction | Yes, under general permission |
Agricultural land | No, not permitted |
Farmhouses | No, not permitted |
Plantation property | No, not permitted |
Agricultural land received as inheritance or gift | Yes, inheritance only |
There is no cap on how many residential or commercial properties an NRI or OCI can own in India, according to the Ministry of External Affairs' RBI FAQ. Among residential options, 3 BHK Flats in Zirakpurremain especially popular with NRI families who want a comfortable mid-size home close to Chandigarh, with the flexibility to use it as an investment propertyor move in later. It is not just an investment. It is a plot or a 3 BHK flat in Mohali or the family house rebuilt in a hometown you still call home.
One rule catches people by surprise every time. If you inherit agricultural land as an NRI, you are allowed to hold it. But if you later want to sell it, you can only sell to a resident Indian. You cannot sell inherited agricultural land to another NRI as per Indian Government rule. Farmhouses and plantation property follow the same purchase restriction, no exceptions.
Also, this general permission is automatic. NRIs do not need to file any intimation with the Reserve Bank of India after buying a standard residential or commercial property. No RBI approval letter required.
This is where FEMA rules for NRI property purchase get strict and most first-time buyers slip up here.
Every payment must move in Indian Rupees, through proper banking channels. Foreign currency wired directly, cash handed over on a visit home or a payment made outside India - none of these are permitted under FEMA guidelines NRI real estate India rules recognise.
Three account types can legally fund your purchase.
Account Type | Full Name | Best Suited For |
NRE Account | Non-Resident External | Foreign earnings, fully repatriable |
NRO Account | Non-Resident Ordinary | Indian earnings like rent or dividends, limited repatriation |
FCNR(B) Account | Foreign Currency Non-Resident | Foreign currency deposits, repatriable in that currency |
Cash transactions and traveller's cheques are banned outright, no matter how small the amount. If you book a flat with a developer and later cancel, your refund can go back into your NRE account, but only if the original payment came from NRE or FCNR funds.
No and most NRIs do not. Indian banks actively compete for NRI home loan business and rates in 2026 range between 7.15% and 8.85% per annum, depending on the lender and your profile - whether you are buying to live in eventually or purely as an investment property.
Bank | Interest Rate (p.a.) | Loan Tenure |
State Bank of India | 7.50% to 8.50% | Up to 30 years |
HDFC Bank | 8.15% to 8.75% | Up to 20 years |
ICICI Bank | 8.40% to 8.75% | Up to 30 years |
Bajaj Housing Finance | From 7.15% | Up to 20 years |
Bank of Baroda | 7.50% to 8.50% | Up to 30 years |
Axis Bank | 7.15% to 8.75% | Up to 30 years |
Rates are indicative and move with RBI repo decisions. Always confirm the current figure with your lender.
To qualify, you generally need a valid Indian passport or OCI card, one to two years of stable overseas employment or business income, an active NRE or NRO account, a PAN card and a minimum gross annual income of around ₹5 lakh, though this varies by bank. You do not need to be physically present in India. Loans can be processed entirely through a Power of Attorney.
Loan-to-value limits work on a sliding scale. Banks typically finance up to 90% for properties under ₹30 lakh, up to 80% between ₹30 lakh and ₹75 lakh and up to 75% above ₹75 lakh. Your EMI has to be paid in rupees from an NRE or NRO account and the bank disburses the loan directly to the seller or developer, never into your personal account.
Documents required for NRI property purchase fall into three buckets. Sort these before you start house-hunting and the whole process moves faster.
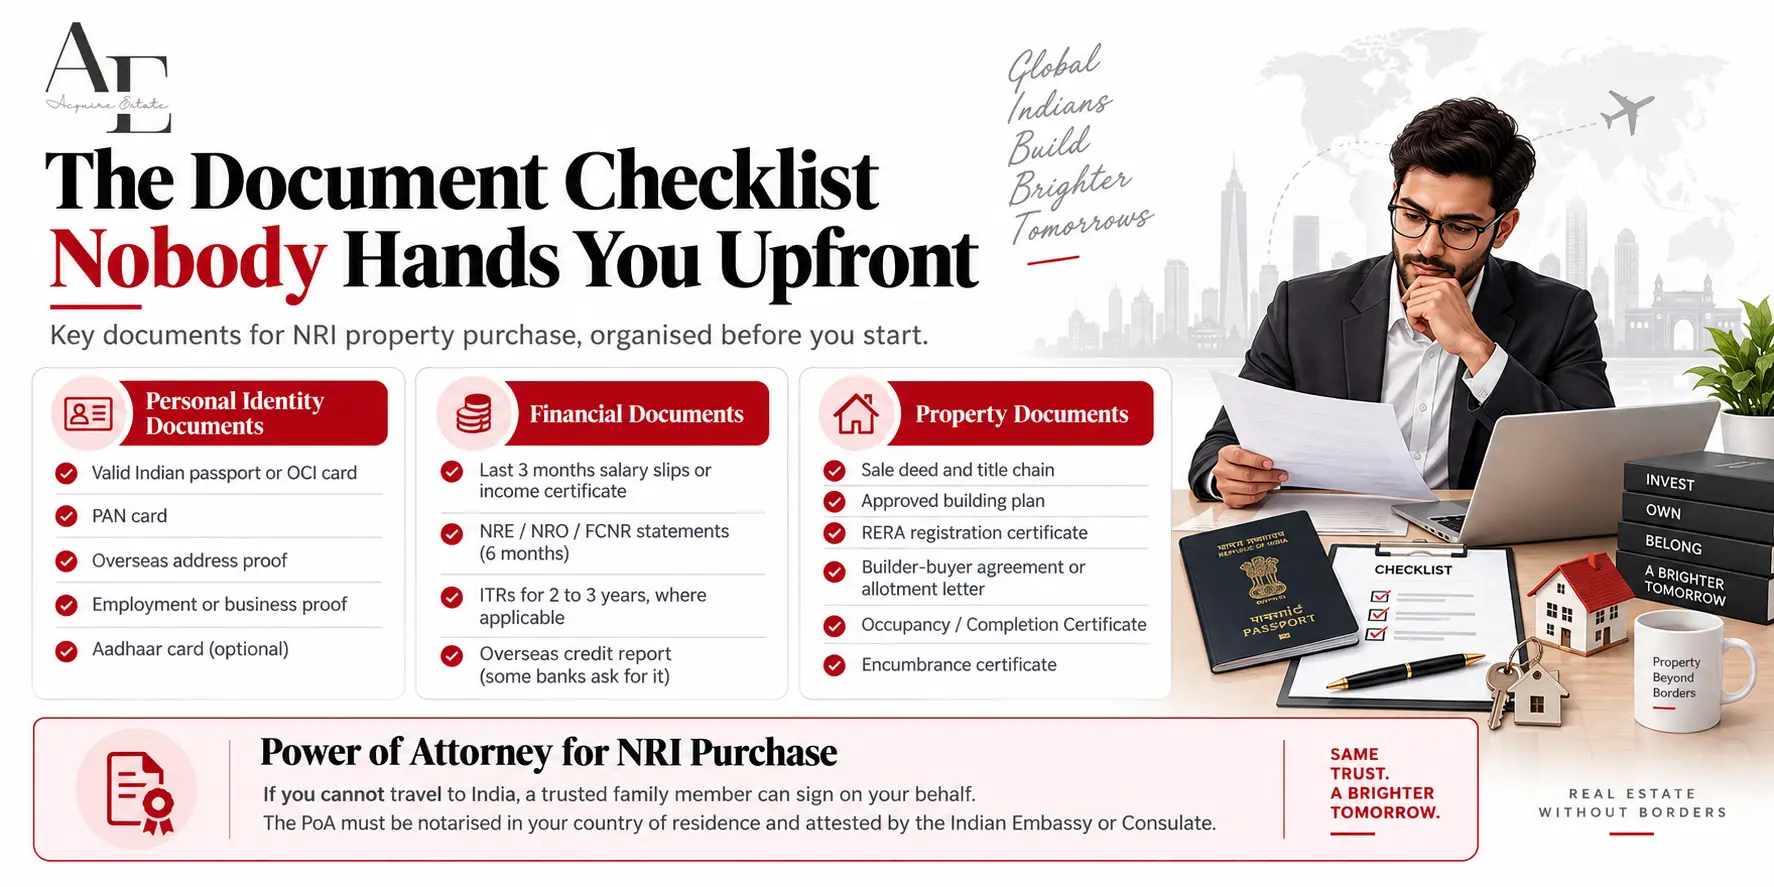
• Valid Indian passport or OCI card
• PAN card, mandatory for every Indian property transaction
• Overseas address proof such as a utility bill or bank statement
• Proof of overseas employment or business
• Aadhaar card, not compulsory but useful if you already have one
• Salary slips or income certificate for the last three months
• NRE, NRO or FCNR bank statements for the last six months
• Income Tax Returns for the last two to three years, where applicable
• An overseas credit report, required by some banks including ICICI and HDFC, usually not older than 45 days
• Sale deed and title chain, ideally going back 15 to 20 years
• Approved building plan from the local authority
• RERA registration certificate of the project
• Builder-buyer agreement or allotment letter
• Occupancy or Completion Certificate for ready-to-move homes
• Encumbrance certificate confirming no pending dues or disputes
If you cannot travel to India for registration, a Power of Attorney for NRI property purchase lets a trusted family member sign and register on your behalf. The PoA must be notarised in your country of residence and attested by the Indian Embassy or Consulate there. This single document, done properly, saves you an expensive trip and weeks of delay.
Tax Deducted at Source, capital gains, stamp duty. These four areas decide how much of your money actually reaches your pocket or the seller's.
Stamp duty and registration charges apply equally to NRIs and resident buyers. In Punjab, stamp duty currently runs at approximately 7% of property value for male buyers, with a 2% concession for women buyers. Registration adds roughly 1% more. Always verify the current rate with the Punjab Revenue Department, since these figures do shift.
For example, on a ₹60 lakh flat, stamp duty works out to about ₹4.2 lakh, plus ₹60,000 registration, adding up to roughly ₹4.8 lakh in transaction costs alone, over and above the property price.
If the Occupancy Certificate has not been issued yet, GST applies. Affordable housing under ₹45 lakh attracts 1% GST, effective rate after abatement. Other residential properties attract 5%. GST does not apply once a project has a valid Occupancy Certificate, which is exactly why many NRI buyers specifically hunt for OC-ready, ready to move flats in Mohali.
When an NRI sells property in India, the buyer must deduct TDS before paying the seller. This obligation, earlier under Section 195, now sits under Section 393(2) of the Income-tax Act, 2025.
Holding Period | Capital Gain Type | TDS Rate |
More than 2 years | Long-Term Capital Gains | 12.5% plus applicable surcharge and 4% cess |
Up to 2 years | Short-Term Capital Gains | As per NRI income tax slab |
NRI seller to NRI buyer, long-term | LTCG | 20% plus surcharge and cess |
NRI seller to NRI buyer, short-term | STCG | 30% plus surcharge and cess |
Here is a tip most people never hear about until it is too late. If you are selling and your actual tax liability is lower than the standard TDS rate. Then you need to apply for a Lower TDS Certificate through Form 13 on the Income Tax TRACES portal before the sale closes. Many NRIs lose money simply because nobody told them this certificate exists.
The 2024 Union Budget reshaped these rates. Long-term capital gains, on property held over two years, are taxed at 12. 5% without indexation benefit. Short-term gains, under two years, are taxed at your regular income slab rate. This applies even if you live abroad permanently and never bring the money into India.
Two exemptions are worth knowing. Under Section 54, reinvesting long-term gains into another residential property within two years of sale can exempt you from this tax. Under Section 54EC, investing in specified bonds like NHAI or REC bonds within six months exempts gains up to ₹50 lakh.
Renting out your Punjab property? That income is taxable in India, same as it would be for a resident landlord. After a standard 30% deduction for repairs and maintenance, plus home loan interest if applicable, the balance gets added to your Indian income and taxed at slab rates.
Tenants paying rent to an NRI landlord must deduct 30% TDS under Section 393(2). Punjab's Tricity belt has increasingly earned a reputation as a strong rental yield propertymarket, thanks to steady demand from IT and aviation sector professionals.
If you are an NRI, you may end up paying tax on the same property income twice, once in India and once in the country you live in. This is where DTAA helps you.
India has signed DTAA agreements with countries like the USA, UK, Canada, Australia and UAE. These agreements make sure that you are not taxed twice on the same rental income or capital gains.
Depending on the country, you either get a tax credit or an exemption. To claim DTAA benefits, you need a Tax Residency Certificate (TRC) from your resident country and Form 10F. Always check your specific country's DTAA terms with a tax expert, since rates and rules differ.
Foreign Tax Credit (FTC) works alongside DTAA and gives you relief when you have already paid tax on your Indian property income in your country of residence. Simply put, you can claim credit for the tax already paid abroad against your tax liability in India, so you don't pay full tax twice on the same earnings.
This applies to rental income and capital gains from property sales. To claim FTC, you need proof of tax paid abroad, usually a certificate from the foreign tax authority and you must file Form 67 with the Income Tax Department before your return deadline. Keep all receipts safe, since claims without proper proof often get rejected.
Yes and this is one of the most common questions NRI buyers ask before they even sign a booking form.
Sale proceeds can be repatriated up to the original foreign exchange amount paid or through NRE and FCNR sources
Repatriation from an NRO account is capped at USD 1 million per financial year, running April to March, after all taxes are cleared
Repatriation of sale proceeds from NRE or FCNR-funded property is limited to a maximum of two residential properties
Proceeds from inherited agricultural land, farmhouses or plantation property cannot leave India at all. That money must stay within the country
To complete repatriation, you need to submit Form 15CA online through the Income Tax portal, along with Form 15CB, a certificate from a Chartered Accountant confirming your tax compliance. Keep every purchase document, sale document and tax receipt on file. The Income Tax Department can ask for these years after the deal closes.
Punjab's real estate map has shifted hard toward the Chandigarh Tricity belt over the past few years and Mohali sits right at the centre of it, making it one of the most active hubs for NRI real estate investment Mohali activity today.
The best areas to buy property in Mohali for NRI investors right now share three things: RERA-registered projects, proximity to the international airport and strong rental demand from IT and aviation sector professionals.
Sectors along the Airport Road, the developing zones near Aerocity and the New Chandigarh corridor toward Mullanpur have all seen sustained price appreciation, backed by planned metro connectivity and highway upgrades.
For many NRIs, luxury apartments in Mohali in these belts consistently rank among the best property for NRI investment, thanks to appreciation potential paired with steady rental demand.
Zirakpur, meanwhile, appeals to a different kind of NRI buyer, often someone returning to their own district or looking for lower entry prices with steady long-term appreciation as regional infrastructure catches up.
Whichever city you choose, treat due diligence as non-negotiable, not optional paperwork.
Property title verification NRI: Trace ownership back at least 15 years. A single break in the chain can trap your money in litigation.
Encumbrance certificate property check: Always pull a fresh encumbrance certificate from the sub-registrar's office. It confirms the property carries no pending loan or legal dispute.
Power of attorney for NRI property purchase: If someone is signing on your behalf, get that PoA drafted by a lawyer who specialises in NRI transactions, not a generic template.
Property lawyer for NRI India:Hire one before you pay a rupee in token money, not after a problem shows up.
Virtual property inspection India: Ask for a live video walkthrough before you commit. Reputable developers and agents now offer this as standard practice.
Red flags in property documents India:Watch for mismatched survey numbers, an unusually low circle rate compared to market price, missing RERA registration or a seller unwilling to share original documents. Any one of these is reason enough to walk away.
Acquire Estate is a top real estate company in Zirakpur, Mohali, Panchkula and Chandigarhmakes this entire process easier, since an established local partner can verify listings, confirm RERA status and support embassy-attested Power of Attorney paperwork on your behalf.
1. Confirm your NRI or OCI status and shortlist RERA-registered projects only.
2. Open or activate your NRE, NRO or FCNR account with an Indian bank.
3. Get your PAN card in place if you do not already have one.
4. Arrange your home loan pre-approval, if you plan to finance the purchase.
5. Verify title, encumbrance certificate and RERA status before booking.
6. Sign the builder-buyer agreement and pay through approved banking channels only.
7. Complete registration in person or through a notarised, embassy-attested Power of Attorney.
8. File the correct TDS forms under the current Section 393 framework, not outdated ones.
9. Keep every document safely filed for future resale, taxation or repatriation needs.
NRI property buying in India rewards people who prepare and punishes people who rush. The rules around FEMA, tax and documentation are not designed to trip you up. They exist to protect both the buyer and the country's financial system and once you understand them, the process becomes genuinely manageable.
2026 has already brought one major shift, with the new Income-tax Act renumbering the sections your lawyer and CA rely on daily. NRI property buying in India done through a source that has not updated its information can cost you real money and real time. Work only with advisors, agents and platforms that are current on Section 393, Form 141 and the FEMA rules that actually apply today.
Whether you are eyeing a 4 BHK flats in Mohali or a plots in Mohali, treat NRI property buying in India carefully. The same way you would treat any major financial decision made from thousands of miles away. Verify everything, trust nothing blindly and keep paperwork ready before you need it.
Choose an investment propertythat also works as a genuine rental yield propertyand done right, NRI property buying in India connects you back to home in the most lasting way possible.
Acquire Estate provides project data, builder profiles and investment information for real estate across the Chandigarh Tricity and other regions. Coverage includes Mohali, Zirakpur, Panchkula and developments across Punjab, Haryana, Himachal Pradesh, Maharashtra, Goa and Delhi-NCR, intended to help buyers and NRIs evaluate options before making a purchase decision.
1.Can an NRI buy property in India without visiting the country?
Yes. A Power of Attorney, notarised abroad and attested by the Indian Embassy or Consulate, allows a trusted representative to sign and register the property on your behalf.
2. Can an NRI buy agricultural land in India?
No. NRIs cannot purchase agricultural land, farmhouses or plantation property. Inherited agricultural land can be held, but it can only be sold to a resident Indian, not to another NRI.
3. Which account should I use to fund my property purchase?
Use an NRE, NRO or FCNR account. Cash payments, traveller's cheques and payments made outside India are not permitted under FEMA.
4. What is Form 141 and why have I not heard of it before?
Form 141 is the new challan-cum-statement introduced under the Income-tax Act, 2025, effective 1 April 2026. It replaces the earlier Form 26QB along with three other forms and covers TDS deducted under Section 393(1).
5.Is there a limit on how many properties an NRI can own in India?
No. There is no cap on the number of residential or commercial properties an NRI or OCI can own, as confirmed by the Ministry of External Affairs' RBI FAQ.
6. How much TDS applies when an NRI sells property?
Long-term capital gains attract 12.5% TDS plus surcharge and cess, under the new Section 393(2). Short-term gains are taxed at the applicable income slab rate.
7. Can sale proceeds be sent abroad?
Yes, subject to conditions. Repatriation from an NRO account is capped at USD 1 million per financial year and only after taxes are settled.
8. Do NRIs get home loans in India?
Yes. Most major Indian banks offer NRI home loans, with 2026 rates ranging from around 7.15% to 8.75% per annum and no requirement to be physically present in India.
Home construction in India tells the story of a family's dreams, savings and years of hard work. This guide walks throug...
Thinking of buying into a gated society in Mohali, Zirakpur, or New Chandigarh? This guide breaks down how maintenance c...
A practical, RERA-verified 2026 guide to 3 BHK flats in Mohali covering top gated society projects, price per sq ft, car...
Hi there! How can we help you today?